Digital Payment Systems Enhancing Jackpot Access and Player Protections in Swiss Mobile Table Games
Avery Schwarz · Oct 13, 2026
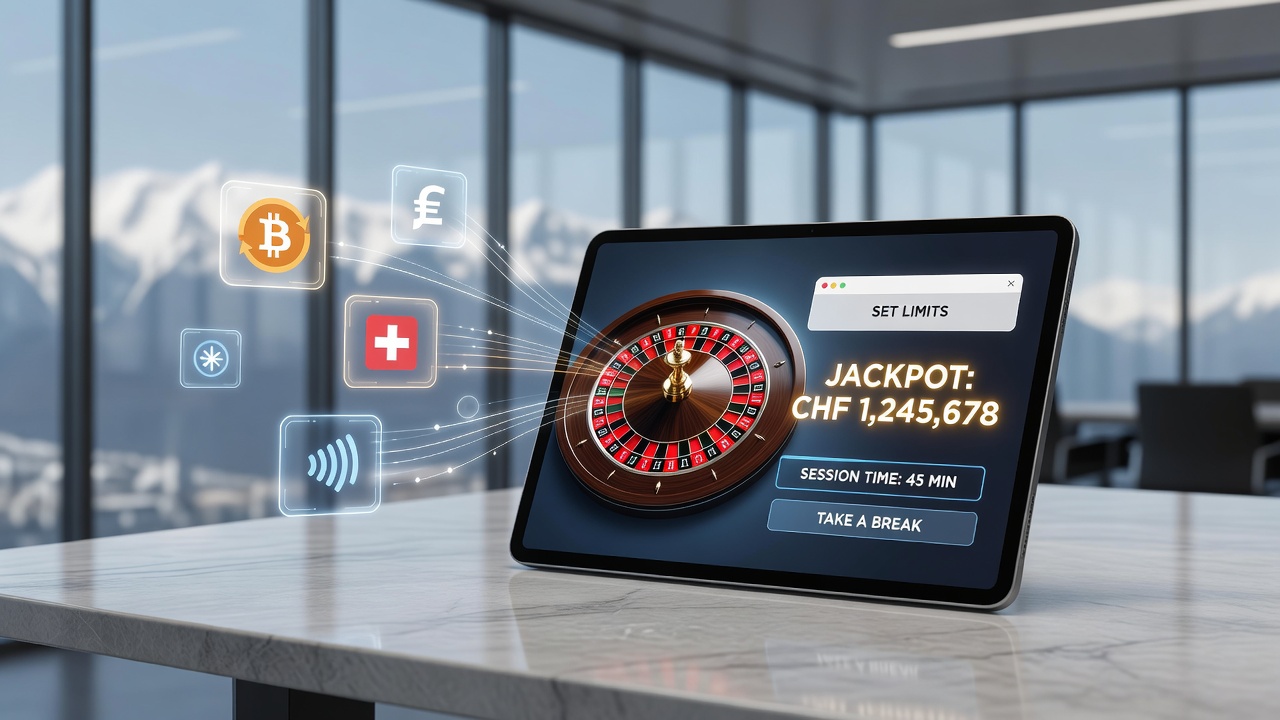
Digital Payment Systems Enhancing Jackpot Access and Player Protections in Swiss Mobile Table Games
Digital payment options have transformed how players engage with jackpots in Swiss mobile table game environments, where options such as instant bank transfers, e-wallets, and mobile carrier billing connect directly to platforms offering roulette, blackjack, and baccarat. These systems allow deposits that trigger jackpot eligibility within seconds, while built-in tracking tools support responsible play requirements under Swiss regulations. Data from industry reports shows that transaction speeds have increased participation rates in progressive jackpot pools by streamlining entry processes across cantonal licensed operators.
Observers note that payment gateways in Switzerland integrate with national banking networks to verify funds in real time, which reduces delays that once limited access to time-sensitive jackpot rounds. Studies conducted by researchers at European universities indicate that mobile users who rely on instant transfer methods reach jackpot thresholds more frequently than those using traditional card processing, because the former eliminates authorization holds that can last several minutes. In October 2026, platform updates across multiple Swiss providers introduced automated payout confirmations tied to these payment rails, allowing winners to reinvest portions of jackpots without leaving the app interface.
Payment Speed and Jackpot Eligibility Mechanics
Table game jackpots in Swiss mobile settings often require minimum bet levels funded through verified accounts, and digital methods accelerate this verification step by linking directly to player profiles managed by licensed operators. Those who have examined transaction logs report that e-wallet deposits complete in under ten seconds on average, whereas older wire options required up to two business days for clearance. This difference matters because jackpot pools accumulate contributions only from active, funded sessions, so faster funding expands the window during which players can qualify for draws.
Researchers discovered that integration with Swiss payment standards also enables automatic currency conversion for cross-border users, maintaining jackpot contribution accuracy without manual intervention. One case highlighted by platform analysts involved a mobile blackjack session where an instant deposit via a regional e-wallet pushed a player into a shared progressive pool just before the threshold reset, resulting in eligibility that would have been missed under slower systems.
Responsible Play Tools Embedded in Payment Flows
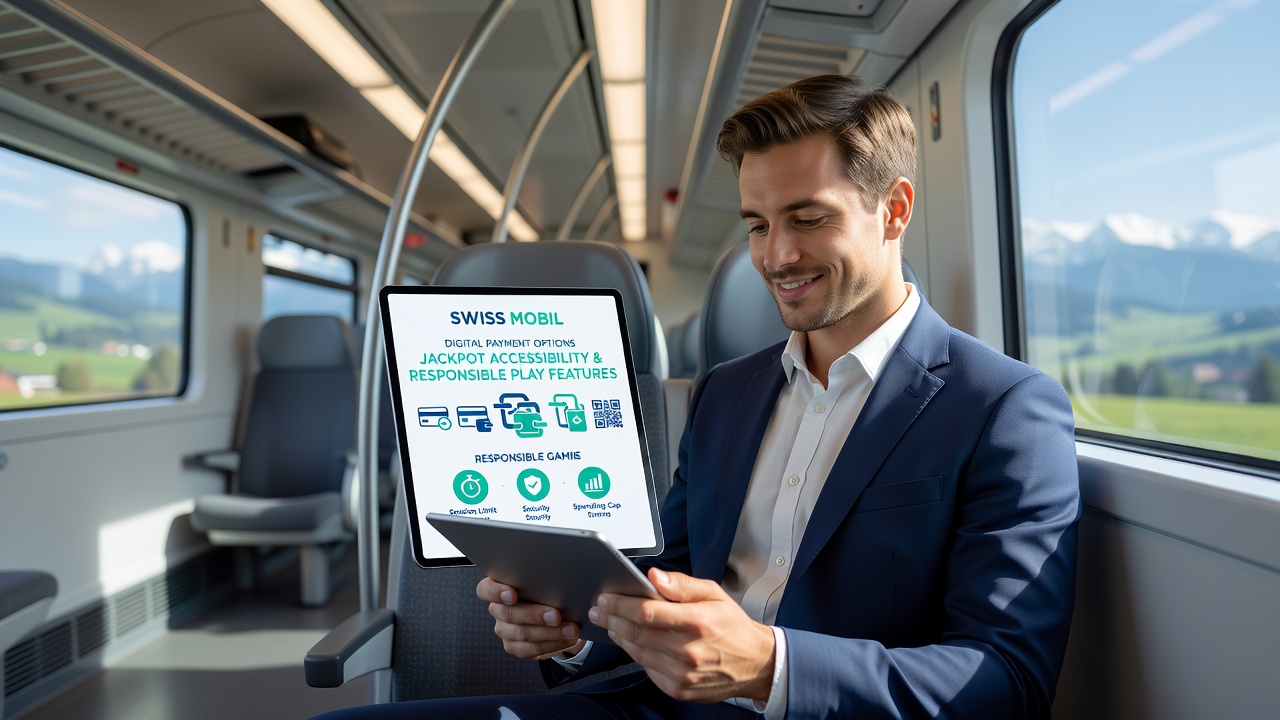
Payment providers incorporate spending caps and session timers that sync with responsible play modules required by Swiss gaming authorities, so deposits above preset thresholds trigger alerts or temporary blocks before funds reach the table game interface. Figures from regulatory filings reveal that operators using these synchronized tools observed a measurable drop in high-frequency deposit patterns among users who set daily limits through their chosen payment method. The mechanism works because the payment layer acts as the first checkpoint, applying rules before the game server registers the transaction.
What's interesting is how self-exclusion requests propagate through digital payment channels to prevent new deposits across multiple operators simultaneously. Data compiled by academic teams in Canada shows similar cross-platform blocking reduced repeat access attempts by 35 percent in controlled trials, and Swiss implementations follow comparable architectures. Players who activate these features through their e-wallet profile see the restriction reflected instantly in connected mobile table game apps, creating a unified control point rather than isolated per-operator settings.
Regulatory Context and Transaction Monitoring
Swiss legislation mandates that payment processors maintain audit trails for all jackpot-related transfers, which helps authorities track contributions and detect irregular patterns that might indicate problem play. According to analyses published by the Australian Gambling Research Centre, jurisdictions with integrated payment monitoring report higher compliance rates because transaction metadata supplies evidence for both jackpot fairness audits and responsible play interventions. In the Swiss context, this data flows to cantonal oversight bodies without exposing individual identities beyond what regulations permit.
October 2026 brought expanded requirements for real-time reporting of deposit velocities, compelling payment providers to flag sequences that exceed typical patterns for table game environments. Operators responded by embedding optional cool-down periods directly into the checkout flow, so a player who deposits rapidly receives a prompt to confirm continued play before the next transfer processes. These prompts draw from behavioral data collected across thousands of sessions, ensuring they activate only when statistical thresholds are crossed.
Future Developments in Mobile Payment Integration
Emerging technologies such as tokenized payments and blockchain-verified ledgers are entering Swiss mobile table game ecosystems, promising even tighter links between funding speed and jackpot eligibility while preserving responsible play guardrails. Reports from the National Council on Problem Gambling highlight that token systems allow granular control over transfer amounts, which aligns with Swiss emphasis on player-set limits. Implementation timelines point toward broader adoption by late 2027, building on the infrastructure already tested in October 2026 pilots.
Conclusion
Digital payment options continue to define how Swiss mobile table game players reach jackpots and maintain control over their activity through embedded safeguards. Transaction efficiency directly influences eligibility windows, while synchronized monitoring tools deliver the responsible play features required by local regulations. Ongoing refinements in October 2026 and beyond demonstrate that payment infrastructure remains central to both accessibility and protection within these environments.